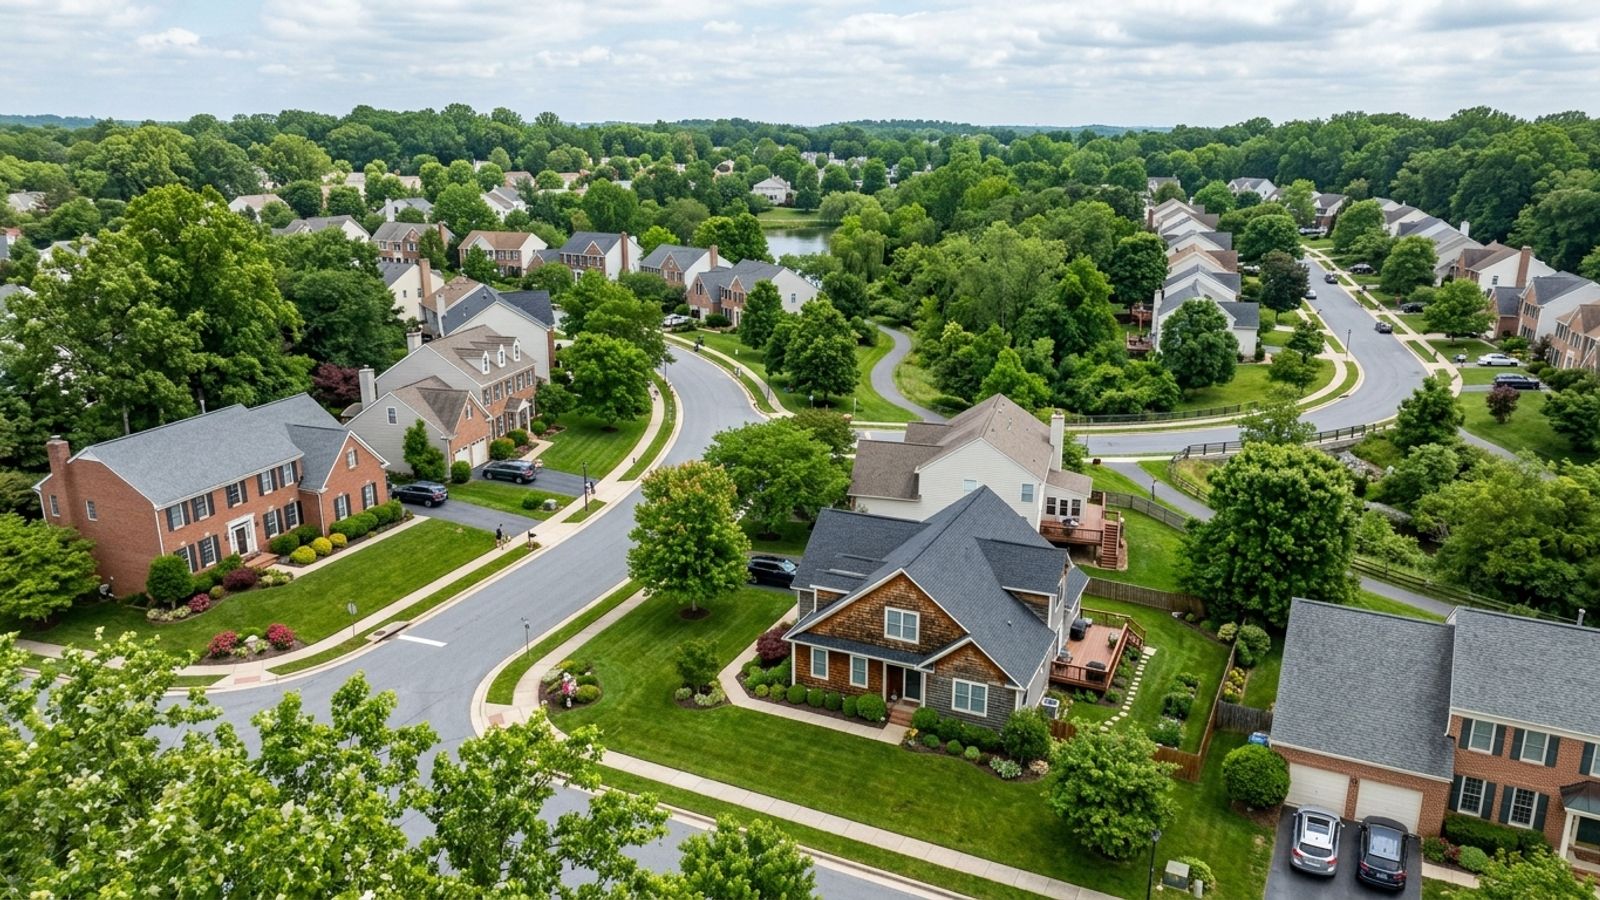
Columbia sits right between Baltimore and Washington, D.C. - a geographic fact that shapes almost everything about living here, from your commute to your monthly budget. When weighing the pros and cons of living in Columbia, MD, these everyday expenses play a major role. It's a planned community, and that planning shows: extensive path systems, village centers, and local amenities are baked into the fabric of the place rather than bolted on afterward.
What that also means is that Howard County comes with its own specific pricing. The area runs at a premium compared to the rest of Maryland, and buyers who don't review local data before starting a home search often find themselves caught off guard.
Overall Cost of Living Index for Columbia, MD
Columbia's cost of living index sits at about 127.9, according to BestPlaces - meaning basic expenses run roughly 28% higher than the national average. Other data aggregators put the premium anywhere from 12% to 38% above a typical U.S. city, so the range is wide, but the direction is consistent.
Housing is the primary driver of that higher index score. If you're relocating from the Midwest or South, expect a real jump in your monthly budget.
How Columbia Compares to Regional Averages
That said, Columbia's costs align closely with the broader Baltimore-Washington metro area - this isn't an outlier so much as a reflection of the regional market. The high median household income in the area helps offset these expenses for many residents, though it doesn't make them disappear.
Housing Costs: Home Prices and Rent Estimates
The median sale price for a home in Columbia is approximately $509,700 as of mid-2026. Homes are spending a median of just 22 days on the market, and the average home is selling for roughly 102% of its asking price. There are around 164 available homes at any given time - tight inventory, by any measure. Multiple-offer situations are not the exception here; they're the expectation.
Average Rental Rates
If you're renting, expect to land somewhere between $2,000 and $2,300 per month on average. That figure shifts depending on which village you're in and whether you're looking at an older apartment or a newer townhome. Zillow and RentCafe both confirm this range, though luxury units push the upper end higher. Budget utilities on top of whatever the base lease shows.
Everyday Expenses Beyond Housing
Basic monthly utilities for an 85-square-meter apartment average around $218 per month. A separate estimate puts the average energy bill closer to $259 per month. Those figures cover electricity, heating, cooling, water, and garbage collection.
Worth knowing: some of the original Columbia villages have older housing stock with lower energy efficiency. If you're looking at homes in those areas, your heating and cooling costs may run higher than the averages suggest.
Transportation and Commuting
Most residents are using Route 29, I-95, or Route 32 to reach Baltimore or D.C. employment centers. Factor in gas, vehicle maintenance, and potential tolls on roads like the ICC (MD 200). The highway access is genuinely good - it's one of the reasons buyers keep targeting this area - but commuting costs add up and belong in your monthly budget alongside housing.
Sales and Property Taxes in Howard County
Howard County's effective property tax rate sits at approximately 1.17% to 1.18% for 2026. That's the highest property tax rate among Maryland's 24 counties - something buyers sometimes don't realize until they're already under contract.
The median annual property tax bill here runs roughly $6,987 to $7,069. Run those numbers through your mortgage payment calculation before you fall in love with a house.
State Sales Tax
Columbia's combined sales tax rate is 6%, which is entirely the Maryland state sales tax. There's no additional local county or city sales tax applied at the register, so what you see is what you pay.
Local Salaries and Household Income
Columbia's median household income is about $166,556 - nearly 105% higher than the national average. The proximity to federal agencies, defense contractors, and major healthcare systems is what supports those earning levels. A household at or near this median can generally manage the local housing costs and Howard County property taxes, though it still requires careful planning.
Factoring Income into Your Housing Budget
Lenders are going to look at your gross monthly income when determining what you qualify for. With a median sale price near $510,000, your debt-to-income ratio matters. Account for local tax rates and any community association fees before you settle on a number - those line items affect your actual monthly payment more than buyers usually anticipate.
Factors Driving Columbia's Prices
The geography does most of the work here. Sitting midway between Baltimore and Washington, D.C. means Columbia draws from two major job markets simultaneously, and that creates consistent housing demand. There's no slow season where inventory quietly builds up.
The planned infrastructure adds another layer - miles of paved pathways, community pools, village centers. Those amenities don't maintain themselves, and the local assessments that fund them are part of the real cost of owning here.
Market Competition
Homes are selling above list price and clearing the market in about three weeks. Limited inventory forces buyers to move quickly and bid aggressively, which keeps property values stable even when broader national markets soften. That's useful if you're a seller, and something to plan for if you're a buyer.
Comparing Columbia to Baltimore and Nearby Areas
Baltimore generally offers lower median home prices and a lower overall cost of living. That's a real difference worth running the numbers on.
But Baltimore City residents pay higher local property tax rates than Howard County residents, and that changes the monthly payment comparison more than the sticker price alone suggests. Don't compare asking prices in isolation - use a local cost of living calculator to look at actual property tax and commuting costs side by side.
Finding Value in Howard County
Columbia is one of the more expensive parts of the county, but buyers willing to look at adjacent towns or older condominium communities sometimes find lower price points. Townhomes in Columbia's older villages tend to offer a more accessible entry than detached single-family homes, if that fits what you're looking for.
Pros and Cons of Buying in Columbia
The location works. Easy highway access, extensive outdoor recreation, large retail like The Mall in Columbia - it's genuinely convenient. The planned separation of commercial and residential spaces is something a lot of buyers specifically want, and Columbia delivers that.
The trade-off is real, though. The highest property tax rate in Maryland, plus a cost of living index running 28% above the national average, adds up. Those aren't reasons to rule it out, but they're reasons to go in with your eyes open.
Making the Decision
Weigh the location's convenience against the ongoing costs - property taxes, community fees, commuting expenses. Touring different villages and reviewing recent sales data will tell you more than any index number. What looks expensive on paper can make sense for the right household; what looks affordable can get complicated once all the carrying costs are on the table.
Frequently Asked Questions
Is it more expensive to buy a house in Columbia, MD compared to nearby Baltimore or Washington D.C.?
Yes, Columbia is generally more expensive than Baltimore, which has a lower median home price. It's often less expensive than buying a single-family home directly inside Washington, D.C. Columbia's median home price sits around $509,700.
How much is the Columbia Association (CPRA) annual charge and does every homeowner have to pay it?
Most properties in Columbia are subject to the Columbia Park and Recreation Association (CPRA) annual charge. The exact amount depends on the property's assessed value, and it's a mandatory fee for homes within the association's boundaries. Check the specific property listing to confirm the exact annual charge before you make an offer.
Are there additional village HOA fees on top of the CPRA assessment when buying in Columbia?
Yes. Depending on the specific neighborhood, there may be an additional homeowners association fee on top of the CPRA charge. Many townhome and condominium communities in Columbia carry their own local HOA dues. Ask to see all community disclosures before you commit.
What should I expect to pay in Howard County property taxes for a home in Columbia?
Howard County's effective property tax rate is roughly 1.17% to 1.18%. For a typical home in Columbia, the median annual property tax bill runs roughly $6,987 to $7,069.
What salary do you need to make to live comfortably and afford a home in Columbia, MD?
It depends on your down payment and existing monthly debt, but the median household income in Columbia is about $166,556. Earning near that median generally allows buyers to manage the area's $510,000 median home prices and local tax rates.
How much are average monthly utilities for a typical single-family home in Columbia?
Basic monthly utilities for an apartment average around $218, while a separate estimate puts the average energy bill at about $259 per month. Larger single-family homes will likely run higher for heating and cooling.
FROM OUR BLOG
The Role of a Probate Attorney for Real Estate Sales in Ellicott City, MD
The median home sale price in Ellicott City, MD sits around $718,000. Inheriting a property here is a significant financial event - but you can't simply list the house with a probate real estate agent in Ellicott City, MD and wait for the wire transfer. Before ownership can transfer, the court has t
What to Expect When Buying a Probate Home in Ellicott City, MD
The median home sale price in Ellicott City, MD sits around $718,000. Inheriting a property here is a significant financial event - but you can't simply ask a probate real estate agent in Ellicott City, MD to list the house and wait for the wire transfer. Before ownership can transfer, the court has
What to Expect From Trust vs Probate Home Sales in Ellicott City, MD
The median sale price for a home in Ellicott City, MD right now sits at roughly $718,000. With only about 1.7 months of housing supply available, buyers are watching every new listing - including properties that come to market after an owner passes away. Sellers handling these complex transfers ofte
Welcome to Winning Edge Real Estate a Family Owned and Operated Real Estate Brokerage where Winning Matters. We serve all of your real estate needs in and around the Baltimore / Washington Corridor. The Company is run by Jim Bim, Broker of Record, his son's Grant Bim and Weston Bim are Sales people within the company. Jim, Grant and Weston work to help their Sellers & Buyers accomplish their real estate goals while the Office Manager, Valerie Bim, and our Assistant, Kimberly make sure that homes go from "FOR SALE" to "SOLD" smoothly while making sure to keep you informed every step of the way. As real estate specialists we are experts in representing both home Sellers and home Buyers. We can help with general residential home / town home / condo resale, new homes, custom home construction, land sale, sub dividing acreage, as well as investment property. We are very knowledgeable of Howard County, Maryland as we have lived in the area for 40+ years. Due to our clients moving throughout the state, we also are very knowledgeable of Anne Arundel County, Carroll County, Frederick County, Baltimore County and Montgomery County. We actively work on a daily basis in areas that include: Fulton, Ellicott City, Columbia, Mount Airy, Clarksville, Woodstock, Jessup, Marriottsville, Glenelg, Glenwood, West Friendship, and everywhere in between. We also service Western Baltimore County which includes Arbutus, Halethorpe, Catonsville, Owings Mills and Reisterstown. We provide a free Maryland Real Estate search where we feature Howard County, Carroll County, Baltimore County, and Anne Arundel County real estate that will allow you to find homes, condos, townhomes, new homes, luxury homes, or even acreage, lots, or investment properties. Do you want to invest for your future, but you are not sure how to make the leap to become a real estate investor? We can help you find the right money making property, rent your property, and manage your property. If you have the desire to be a real estate investor, then we have the knowledge and know how to get you to real estate investor success. Quick Stats/Highlights: 100% of asking price (average) 63+ active listings Serving: 8 Maryland counties Hundreds of 5-star reviews